

The human brain was not designed to make us exceptional. It was designed to keep us alive: conserve energy, avoid unnecessary risk and seek safety. High performance was not really in the brief.
Left to our own devices, we do not naturally drift upwards towards our full potential. We drift towards whatever feels safer and easier.
High performance is not the natural state. It is the exception.
And overriding the default takes energy.
Manage energy, not time
Fit to Lead began with that one idea.
Most CEOs can tell me where every hour of the previous week went. Far fewer can tell me what the week took out of them, which parts gave something back, or why.
The calendar is the thing everyone optimises. But time is fixed. Energy is not. Energy decides what those hours are actually worth.
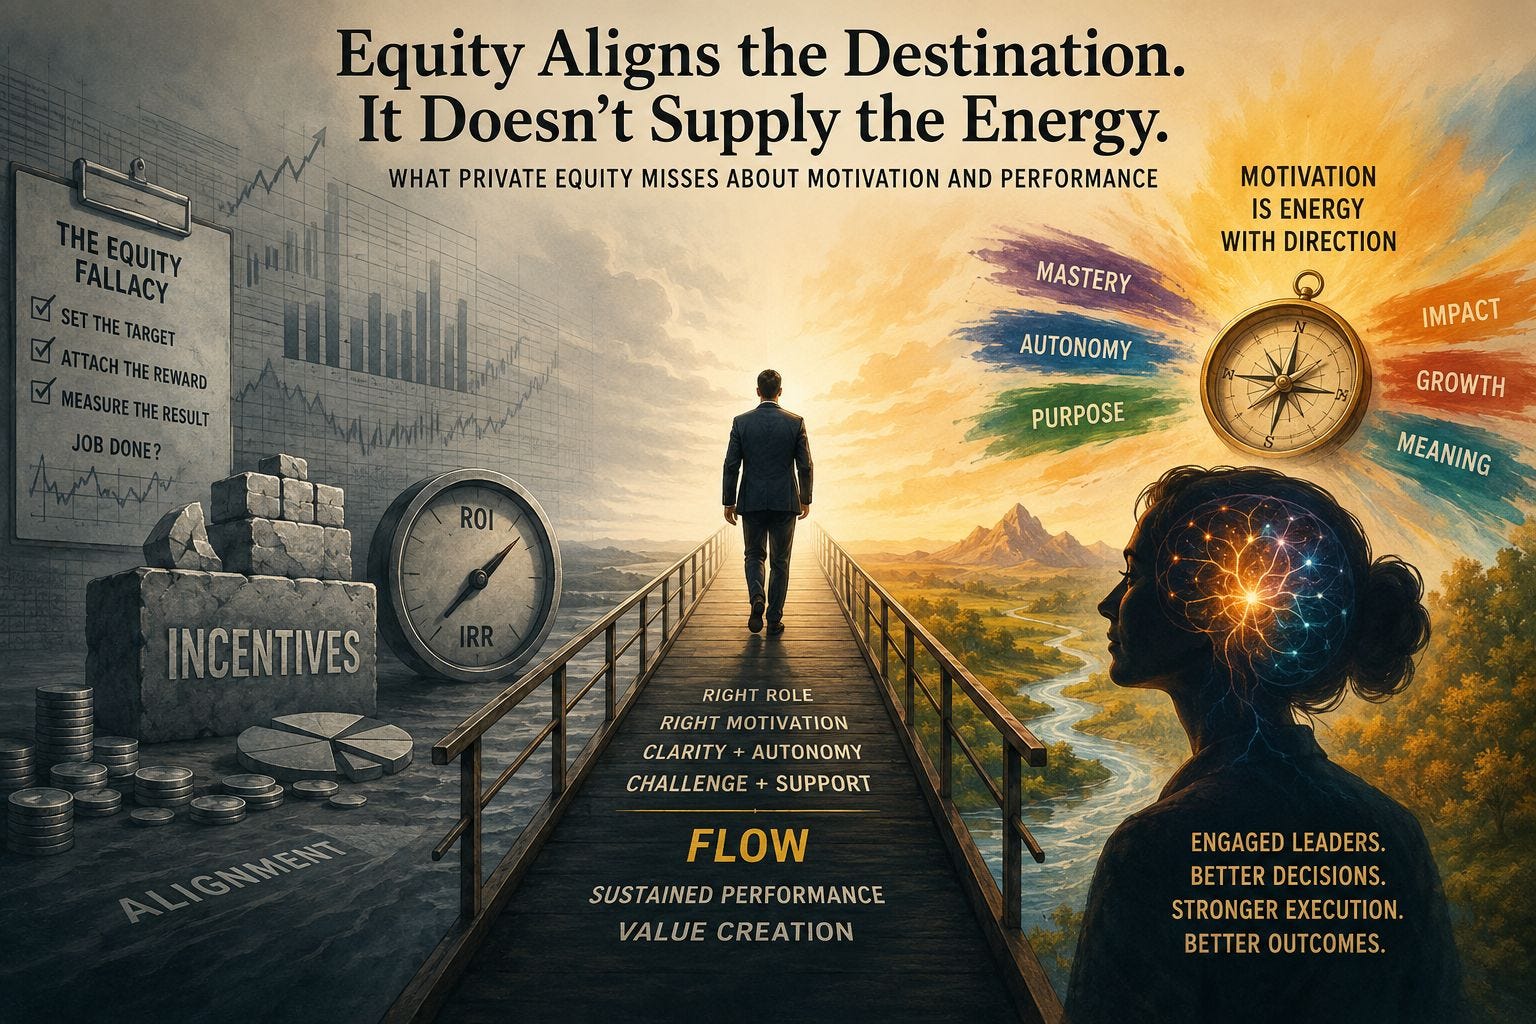
Motivation is energy with direction. It is the internal reason that releases effort towards something.
Two CEOs can run identical weeks. One finishes flat and resentful; the other finishes tired but still wants more.
Same hours. Very different businesses three years later.
Private equity measures hours, output, and the incentive plan. It rarely measures the energy underneath them.
The equity fallacy
PE is built on a reasonable assumption. Give an operator equity, align her interests with the fund’s, and motivation largely takes care of itself.
That is not wrong. It is just dangerously incomplete.
Equity can align the destination. It cannot supply the energy for the journey.
PE likes incentives because they are tangible.
Set the target. Attach the reward. Measure the result. Job done.
Except that CEO performance is not a simple transaction where more incentive reliably produces more output.
The role depends on judgement, imagination, candour, resilience, and the ability to do difficult things whose value may not show up for years. A stronger financial incentive does not automatically produce more or a better version of any of them.
A CEO can be extremely motivated by the exit and still avoid building the team, confronting the founder, investing for the longer term or making herself less important to the business.
The incentive may be working perfectly while the role is being done badly.
PE measures the level of financial motivation. It is much less curious about where that motivation points, whether it fits the work and how long it will last.
The problem is not a lack of money.
It is asking for money to do a job it cannot do.
The average can lie
A six-month case study in James Sale’s Mapping Motivation produced an apparently uneventful headline. Average motivation across two directorates remained roughly stable at just under 70%.
But underneath that average, one person’s motivation score rose by 38 percentage points while another’s fell by 44.
The average was stable. The people were not.
That is exactly how boards miss what is happening. The engagement score looks steady. The management team is still delivering. Yet one key executive may be gaining momentum while another is quietly checking out.
Averages tell you something about the population.
Businesses are often won or lost by a handful of individuals.
And this is not a soft issue.
Low motivation shows up as slower decision-making, avoided conversations, weak delegation, lost executives, and Value Creation Plan initiatives that never quite move forward.
By the time it appears in the numbers, it has usually been doing damage for months.
The bigger mistake is treating motivation as fixed
What drove someone through the first build and exit may not drive her through the fourth.
Early on, she may have wanted to prove herself, make serious money or notch up another successful exit. Later, she may care more about mastery, freedom, legacy, or simply no longer want the life the role demands.
This matters because PE loves the repeat operator.
Proven. De-risked. She has done it before.
But does she still want to do it again?
Experience is historical. Motivation is current.
A CV tells you what someone did. It does not tell you whether she still wants the work that produced it.
Sometimes what looks like de-risking is simply paying for a previous version of the person.
Motivation also affects more than whether someone burns out.
Highly motivated people are more likely to persist when the work becomes difficult, learn faster, bring discretionary effort, recover from setbacks and keep searching when the first answer does not work.
They do not merely last longer. They are more likely to perform better while they are there.
People who find some reward in the work itself may put in equally brutal hours, but those hours impose a different psychological cost. They want to master the craft, solve the problem or build the business, not merely reach the exit.
At its best, the right combination of motivation, capability and challenge can produce flow, the state Mihály Csíkszentmihályi described as complete absorption in demanding work.
Flow is most likely when the challenge stretches someone’s capability without overwhelming it. A CEO who regularly reaches that state in the important parts of the role is not simply working harder. She is concentrating more deeply and operating closer to her best.
That does not make them immune to burnout. Passionate CEOs run themselves into the ground as well.
But over a PE hold period, a role that allows the CEO to spend enough time in the zone is a serious advantage.
Demotivation rarely arrives with a loud bang. It creeps. A capable person can continue delivering against her own grain for a long time.
What looks like a sudden loss of form is often the end of a slow, largely invisible decline.
High output. Low motivation. No early warning.
Motivation has to fit the job
People draw energy from different sources: security, belonging, recognition, influence, money, mastery, invention, freedom and meaning. Usually, a few matter much more than the rest at any particular point.
One of the easiest mistakes is projection. We assume the person across the table is motivated by the same things we are.
A PE partner driven by achievement, money and winning may assume that more equity is the obvious answer. The CEO may care far more about autonomy, mastery, recognition or having a life outside the business.
Rewarding someone in the way you would want to be rewarded is not the same as understanding what motivates them.
Motivation is not the same as capability. Someone may be good at work that drains her, or energised by work she is not yet good at.
The useful questions are:
What is driving this person now?
How well does the role satisfy those motivations?
Does the work required to succeed provide enough of what motivates her, or does too much of it work against her?
Where there is a mismatch, some of the role may be redesigned.
A CEO who dislikes the mechanics of performance management can get support from HR, delegate more day-to-day management and build stronger leaders below her.
But there is a limit.
She cannot delegate her accountability for the quality of the senior team, avoid confronting serious underperformance or leave difficult people decisions permanently to somebody else.
You can redesign the work. You cannot redesign away the core accountability.
The same principle applies to other motivations.
Recognition, influence and money are not the problem. What matters is how the CEO goes about getting them.
A CEO driven by recognition might build a brilliant team and take pride in its success. Or she might keep herself at the centre because that is where the applause is.
A CEO who values influence might create a robust operating system that helps others act. Or she might insist that every serious decision comes through her.
A CEO motivated by money might build enduring value. Or she might optimise for the next exit at the expense of the business.
Same motivation. Very different behaviour.
So the risk is not merely whether the CEO is motivated. It is about whether her motivations, capabilities, and the role’s essential demands can work together.
But the role itself is only half the equation.
A CEO can be well matched to the job and still be steadily drained by the way the board governs her.
Boards drift towards safety too
When uncertainty rises, the board’s natural instinct is to ask for more information, revisit the decision, narrow the mandate, add another approval and request one more piece of analysis before committing.
Each intervention may be reasonable. Together, they can send a rather different message:
We hired you to make the decisions, but only the ones we would have made ourselves.
The CEO brings a bold proposal. The board waters it down. She comes back with another. Same result.
Eventually, she stops bringing bold proposals, and the board then worries that she has become too operational.
That is not necessarily a failure of courage. It may be learned caution.
The board has taught her what happens when she sticks her neck out, and she has paid attention.
What good boards do differently
A good board creates the conditions in which the CEO’s existing motivation can produce the right behaviour.
That starts with a clear mandate. The CEO should know which decisions she owns, where the board expects consultation and what genuinely requires approval. A good board challenges the thinking without quietly taking the decision back. It tests the assumptions, exposes the risks and demands clarity. Then, unless it is genuinely a reserved matter, they allow the CEO to decide.
It also distinguishes useful information from reassurance reporting.
The question is not whether the board could have more information. The answer to that is always yes.
The question is:
What decision will this information change?
When the honest answer is “none”, the reporting may be serving the board’s anxiety rather than the company’s needs.
Good boards also pay attention to the CEO and the handful of executives carrying the Value Creation Plan, not merely the aggregate engagement score. They notice when the work is creating energy and flow, and when the role or organisation is steadily draining both.
Autonomy without accountability is abdication.
Accountability without autonomy is theatre.
The cheapest edge nobody uses
As the investor Brent Beshore puts it, private equity is, underneath the models, a business of predicting human behaviour.
Everyone models the multiple, margin and cash.
Almost nobody tracks the motivational energy that determines whether people run towards the plan or merely endure it.
The board does not need another company-wide survey.
It needs an honest view of the CEO and the handful of people carrying out the Value Creation Plan.
The mechanism does not need to be complicated. Build a short motivation and role-fit check into the quarterly Chair-CEO conversation, and repeat it with the handful of executives on whom the plan really depends.
Ask:
What parts of the role give you energy or put you in the zone?
What parts are steadily draining it?
Has what motivates you changed?
What can be redesigned or delegated, and what remains a core accountability?
Agree on one or two practical changes. Then check the following quarter whether they made any difference.
Do not ask only whether they are capable or incentivised. Ask whether they still want this particular work, in this particular environment, at this point in their lives.
The competitive edge is not to become softer about performance.
It is to become more precise about what produces it.
Everyone in the deal knows the multiple they paid.
Does anyone know what is actually driving the people who have to deliver it?