

Private equity is obsessed with speed. Speed of value creation. Speed of execution. Speed to exit.
But there is one form of speed that gets almost no attention.
The speed at which the CEO learns.
I’d argue this is one of the clearest differences between good PE-backed CEOs and exceptional ones. Not confidence. Not charisma. Not strategic intelligence. Not even work ethic. Those things matter, but in the PE environment, where the pressure is high, the clock is ticking, and the context keeps shifting, the leaders who pull away have two distinctive habits.
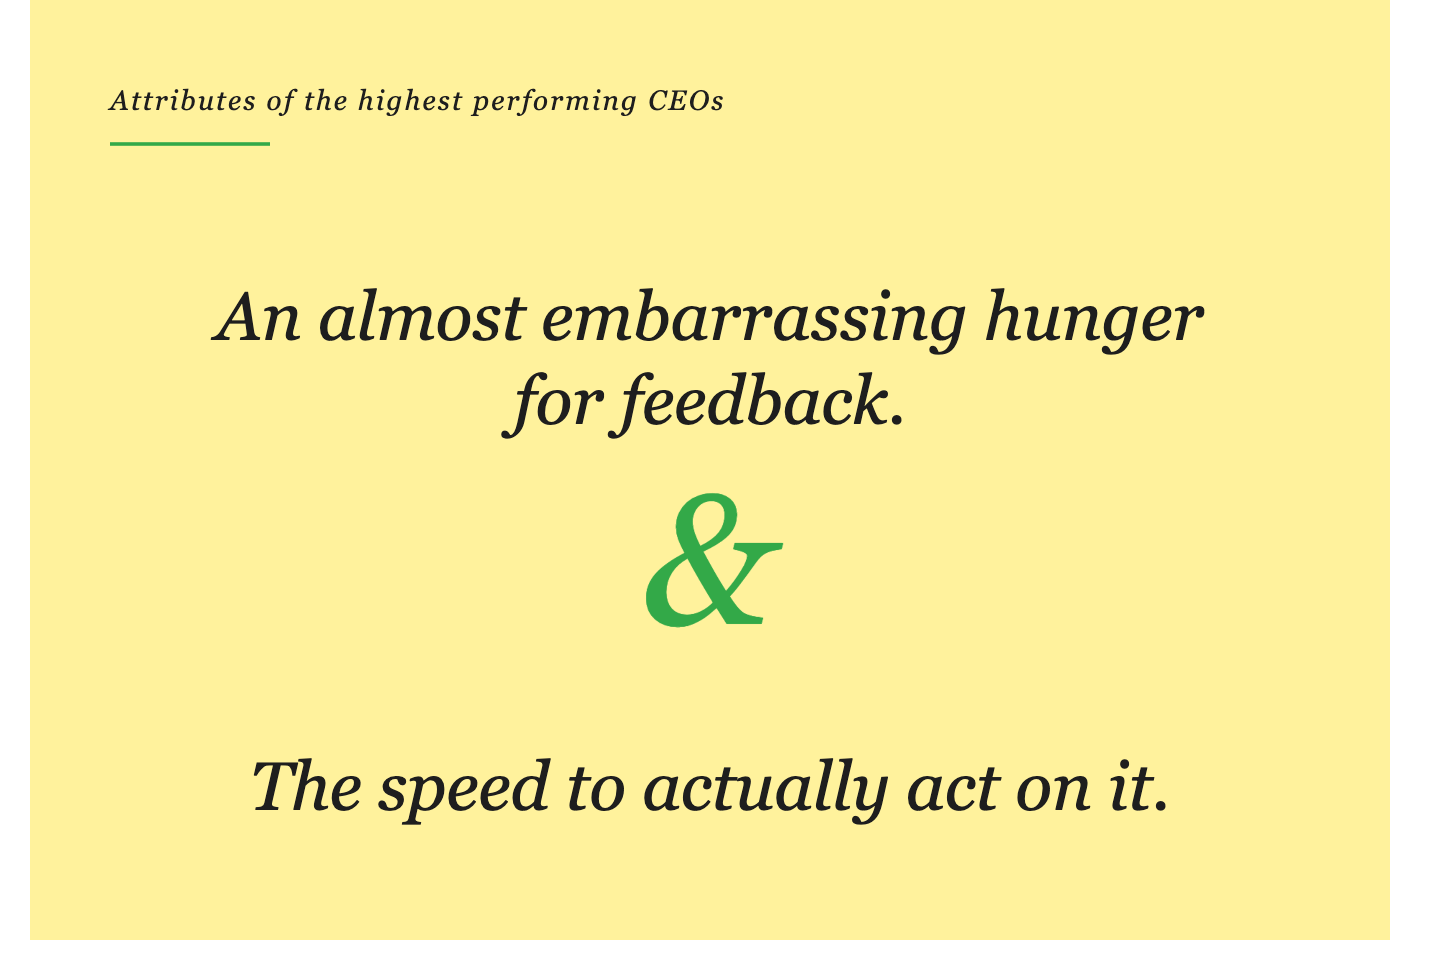
Hunger For Feedback, And The Speed To Act On It
I spend most of my working hours in the PE world - coaching and mentoring CEOs, chairing two CEO groups, evaluating leaders for PE houses, and engaging in conversation with 25+ chief executives each month. No two contexts demand the same kind of CEO. But two commonalities keep showing up among the very best.
The framing comes from Dr Christian Marcoli, the performance coach for elite sport and business, and one of Federer’s early coaches. Marcoli identified the attributes that distinguish the highest performers. Two of them I recognise immediately in the CEOs I’d back without hesitation:
An almost embarrassing hunger for feedback on how to get better.
And the speed to actually act on it.
That’s it. That’s the difference.
The first is not occasional openness to feedback. Not tolerance of it. It is an active, almost impatient desire for it. However experienced these CEOs are, however many times they have done this before, they want to know what they are missing.
The second is operational. You speak with them on a Tuesday. You follow up two weeks later. They have already moved on it - four times. Not once. Four times. They have had the conversation. Changed the meeting rhythm. Tested the message. Asked for the data. Apologised. Stopped doing something. Started doing something.
Average leaders, by contrast, talk about the same thing for hours across months. Sometimes they get to it. Often they don’t.
This is not a minor difference. It is a compounding one. Over a five-year hold period, the gap between a CEO who absorbs and acts fast and one who doesn’t is enormous - in value created, in team performance, in the quality of the exit conversation.
The question for every PE principal reading this is simple. Does your CEO have both? And if they do - what are you doing to feed that hunger?
We’re All In Over Our Heads
There’s a paradox here. Most capable CEOs are reluctant to put their hand up and ask for help. Carol Dweck’s research found the same dynamic in how we praise children. Tell a child she’s smart, and she starts protecting the label - avoiding challenge and giving up more quickly after failure. Tell her she’s worked hard, and she goes looking for the next stretch. The more capable the CEO is perceived to be, the more careful she becomes about protecting that perception. This is why the hungry CEOs we described at the opening are so rare. They have broken the pattern most capable people fall into.
And yet Robert Kegan at Harvard found that most adults - including most leaders - are operating beyond their current developmental capacity. Not because they are weak. Because the demands of modern roles outstrip the developmental stage most adults have reached. VUCA is not a buzzword. It is what every CEO wakes up to. PE ownership intensifies every dimension of it.
The question is not whether your CEO is in over their head. They are. The question is whether anyone is helping them navigate it.
Why PE Still Resists Coaching
I have a love-hate relationship with the PE industry. The love: businesses run better, jobs and wealth get created, and more tax flows to public services. The hate: how it treats the leaders running those businesses.
You’d think the two sides were aligned. Grow the revenue, grow the profit, sell it for more than you bought it for. The problem is that CEOs are from Mars and PE principals are from Venus. Different worldviews. Different daily problems. Neither side fully appreciates the other.
And so the conversation I keep having with PE principals goes something like this:
“We’re not sure coaching is a productive use of CEO time.”
Or: “If we do bring in a coach, it’s for someone who’s struggling. Not for the high performers.”
Or: “That’s what the Chair is for.”
I get over-excited in these conversations, but I love having them! Either you’ve got the wrong coach, or you’ve got a blind spot. If athletes, dancers, and musicians at the top of their field all use coaches, why on earth wouldn’t the CEO of a £200m business?
In Silicon Valley, the question has flipped. It is no longer “Why do you have a coach?” It is “Why haven’t you got one?” Eric Schmidt, initially offended at the suggestion he needed a coach, later wrote of Bill Campbell: “His role was needed from the beginning. I should have encouraged this structure sooner, ideally the moment I started at Google.”
Coaching Is A Vitamin, Not A Painkiller
The block is conceptual. PE treats coaching as a painkiller - something you reach for when the headache arrives. It should be a vitamin. In from day one. Making strong leaders stronger.
Because here’s the thing. The leaders who most need development are not the struggling ones. They are the best ones.
Jeff Bezos put it more plainly in an Amazon shareholder letter: “Coaching is also extended to employees who are excelling and in line for increased responsibilities. In fact, 82% of coaching is positive to employees who are meeting or exceeding expectations.”
Federer won Wimbledon and went straight back to his coach to work on what to improve next. That isn’t insecurity. That’s the disposition of someone who knows their edge is perishable.
The maths is on this side too. Getting a CEO from 0.5x to 1.0x is not where the fund is made. Getting them from 3x to 5x is. Your best performer has the most headroom. That is where development pays back at multiples.
There is no line on the P&L for leadership drag. There should be. It is the problem PE houses cannot see: slow decision-making, unclear accountability, avoided conversations, functional leaders pulling in different directions, and a value creation plan that remains a presentation rather than an operating system. By the time the drag is visible, months of value have already leaked away.
PE firms would never wait until the numbers were broken before putting in financial controls. So why wait until leadership drag is visible before investing in CEO development?
The Conversations Your Chair Can’t Have
The objection I hear most often: “But the Chair already does this. So does the operating partner.”
They don’t. They can’t.
The Chair and the investor directors are judging the CEO’s performance. They appointed her. They can replace her. That power dynamic is not incidental - it shapes every conversation. The CEO knows it. So does the Chair.
When a CEO thinks out loud in front of the Chair, every word is being evaluated — and lands somewhere in the boardroom record. The PE director often overreacts, spreading their anxiety to colleagues and the IC. The CEO learns quickly: thinking out loud has consequences. So she stops doing it when she might need it most.
A coach has significant responsibility but no fiduciary duty to shareholders or creditors. No board seat. No reporting line back to the fund. Nothing the CEO says will affect her position, her reputation with investors, or her next move.
You can’t be developed by the person who can fire you.
It allows a different category of conversation. The doubts that don’t yet have shape. The strategy she half-believes in. The hire she is starting to regret. The relationship with the Chair that is curdling. The exhaustion. None of it belongs on the board pack. It belongs in a room where it can be held, examined, tested — and where she can change her mind without that being read as a wobble.
This is the structural gap. It isn’t that Chairs and PE directors are bad at developing CEOs (although most of them are). It is that the relationship cannot do this work, no matter how skilled the people inside it are.
The Board Your CEO Doesn’t Have
Every PE-backed CEO has a Board for Accountability. Chair, investor directors, NEDs. It shows up reliably and asks hard questions about the numbers.
What almost no CEO has is a Board for Development.
A Board for Development is where the CEO’s learning compounds. Over a five-year hold, that compounding is where value gets made. If the best CEOs are hungry for feedback and quick to act on it, this is the practical infrastructure that feeds the hunger.
It is not another committee or governance forum. It is a set of distinct relationships around the CEO, each doing a different job.
Four working relationships, plus the exemplars she chooses.
The coach helps the CEO think without consequence. A confidential space where she can surface what is genuinely hard without it being read as weakness by the people who determine her future - her patterns, her assumptions, her habitual moves - so she can think properly before the issue becomes publicly expensive.
The mentor helps the CEO learn from someone else’s mistakes. Pattern recognition, distilled from years close to similar situations, so the CEO doesn’t pay full tuition fees for every lesson herself. “I have seen this founder dynamic before. This is where CFO relationships usually go wrong. You are underestimating how long the sales transformation will take.” The best mentors don’t say “do what I did.” They say, “Here is what I noticed when I was close to something similar.”
The sparring partner makes the CEO’s thinking stronger under pressure. The term comes from sport - in Christian Marcoli’s Winning Match, sparring is two athletes going several rounds, hitting seriously but never to win. The point is to find the weak spots so both get stronger. In the CEO context, the sparring partner takes an explicit position on the substance of the CEO’s thinking - the strategy, the hire, the message - and offers a clear counterbalance. They stress-test the decision. They voice uncomfortable truths. They say the thing others are circling but not quite saying. A coach may ask, “What do you notice about your reaction?” The sparring partner is more likely to say, “I don’t think your argument holds. You’re defending this because it’s yours, not because it’s right.” The decision stays with the CEO, but the thinking gets sharper.
This is not what a Chair or operating partner can offer, even when it looks similar. Their pushback is never just a stress test. It always carries an evaluation. And the CEO can’t lose a round and come back sharper without losing standing in the process.
Demanding rather than harmonious. Future-oriented. Productive discomfort. Rarer and more valuable than any of the other three.
The peers remind the CEO she is not alone in the seat. A small group in comparable roles who understand the pressure and offer honest challenge without an agenda. They know the odd loneliness of running a PE-backed business under board pressure while still needing to look confident. Support without ownership rights.
The exemplars raise the bar. Jim Collins originated the concept; Shane Parrish popularised it in Clear Thinking. The exemplars are figures - alive, dead, or fictional - whose judgment, character, or standards the CEO has consciously chosen to emulate. Charlie Munger, who said, “I never allow myself to have an opinion on anything unless I know the other side’s argument better than they do,” can be on the board. So can Indra Nooyi. So can Atticus Finch. The CEO studies them, imagines them watching when she makes a hard call, and asks what they would do. The other four roles feed her hunger for feedback. Her exemplars set the bar for what feedback is worth acting on.
One further discipline. Even hungry CEOs can curate their feedback - listening to the people they trust, explaining away the people they don’t, calling team frustration “noise” and board concern “impatience.” A Board for Development needs a way to bring unvarnished reality into the room: structured 360s, patterns from missed commitments, and honest input from the exec team. Without it, the board becomes a comfortable echo.
Build this from day one of the investment. Not when something visibly breaks. By then, the drag has already compounded.
The Day You Stop Learning
The moment a CEO thinks they’ve got this sorted is the moment they start to lose their edge.
PE loves a confident leader. Confidence without humility, though, is dangerous. You can get away with it for a while. It catches up.
Ask Ron Johnson. He helped build the Apple stores - perhaps the most successful retail concept on the planet. JCPenney head-hunted him to sprinkle the same magic dust. “I’ve got the playbook,” he thought. Seventeen months later, sales and share price had collapsed, and Ron was out.
The best CEOs I know would never have walked in with the playbook. They’d have walked in with a notebook. That hunger - that Marcoli attribute - is precisely what makes them, and keeps them, the best.
Your CEO has a Board for Accountability.
Does she have a Board for Development?